Buyers
Buy With Us
Let us guide you through every step of the VA homebuying process.
- No down payment required with VA benefit
- No private mortgage insurance (PMI)
- Competitive interest rates
- Certificate of Eligibility assistance
- We negotiate hard to protect your interests
- Experienced with VA appraisals & MPRs
VA Qualified Listings
Featured Listings


Billings MT, 2305 Green Valley Drive
- Address2305 Green Valley Drive
- TownBillings
- StateMT
- List Price$474,900


Billings MT, 748 Arbor Hills Drive
- Address748 Arbor Hills Drive
- TownBillings
- StateMT
- List Price$399,900


Shepherd MT, 5612 Meadowmist Drive
- Address5612 Meadowmist Drive
- TownShepherd
- StateMT
- List Price$435,000

Columbus MT, 11 E Upper Flat Road
- Address11 E Upper Flat Road
- TownColumbus
- StateMT
- List Price$649,000

Billings MT, 2170 Greenbriar Road
- Address2170 Greenbriar Road
- TownBillings
- StateMT
- List Price$639,000

Billings MT, 5840 Foxtail Loop W
- Address5840 Foxtail Loop W
- TownBillings
- StateMT
- List Price$479,900

Billings MT, 1308 Cherry Island Drive
- Address1308 Cherry Island Drive
- TownBillings
- StateMT
- List Price$415,000

Billings MT, 5421 Corner Stone Avenue
- Address5421 Corner Stone Avenue
- TownBillings
- StateMT
- List Price$475,000

Billings MT, 1754 Annafeld Parkway W
- Address1754 Annafeld Parkway W
- TownBillings
- StateMT
- List Price$404,892

Billings MT, 1758 Annafeld Parkway W
- Address1758 Annafeld Parkway W
- TownBillings
- StateMT
- List Price$406,102

Billings MT, 6325 Fresh Water Lane
- Address6325 Fresh Water Lane
- TownBillings
- StateMT
- List Price$499,900

Billings MT, 1631 Rosecrans Drive
- Address1631 Rosecrans Drive
- TownBillings
- StateMT
- List Price$385,000

Billings MT, 400 W Daffodil Drive
- Address400 W Daffodil Drive
- TownBillings
- StateMT
- List Price$335,000

Billings MT, 473 Montecito Avenue
- Address473 Montecito Avenue
- TownBillings
- StateMT
- List Price$509,900

Billings MT, 4215 Phillip Street
- Address4215 Phillip Street
- TownBillings
- StateMT
- List Price$310,000

Billings MT, 3501 San Marino Drive
- Address3501 San Marino Drive
- TownBillings
- StateMT
- List Price$590,000

Billings MT, 3020 Edmond Street
- Address3020 Edmond Street
- TownBillings
- StateMT
- List Price$520,000

Billings MT, 632 Antelope Circle
- Address632 Antelope Circle
- TownBillings
- StateMT
- List Price$375,000

Billings MT, 2245 Salinas Circle
- Address2245 Salinas Circle
- TownBillings
- StateMT
- List Price$439,900
VA Buyers Guide
Buying a home with a VA loan in Montana takes five steps. Korynne Kern has worked through each one from the underwriting desk and from the buyer's side. Select a step to see what happens and how the HeroKeys Team helps.
Get Your Certificate of Eligibility
Your Certificate of Eligibility (COE) shows a lender that you qualify for the VA home loan benefit. You can request it online through VA.gov, and many lenders can request it for you. If your service records need extra paperwork, we'll help you gather what's missing so your home search can start on time.
Get Pre-Approved with a VA-Approved Lender
A VA-approved lender reviews your finances and your COE, then issues a pre-approval letter. The letter sets your price range and shows sellers that financing is behind your offer. Questions about loan terms and qualifying go to your lender. Korynne started her career in mortgage underwriting, so she works alongside your lender to keep the paperwork and your home search moving together.
Find a Home That Meets VA Standards
Every home bought with a VA loan has to meet the VA's Minimum Property Requirements (MPRs), such as safe access to the property and a sound roof. We focus your search on Montana homes likely to meet those standards, which matters most for rural properties and acreage. Well, septic, access and zoning details vary by listing, and we'll go through them with you for any home you're considering.
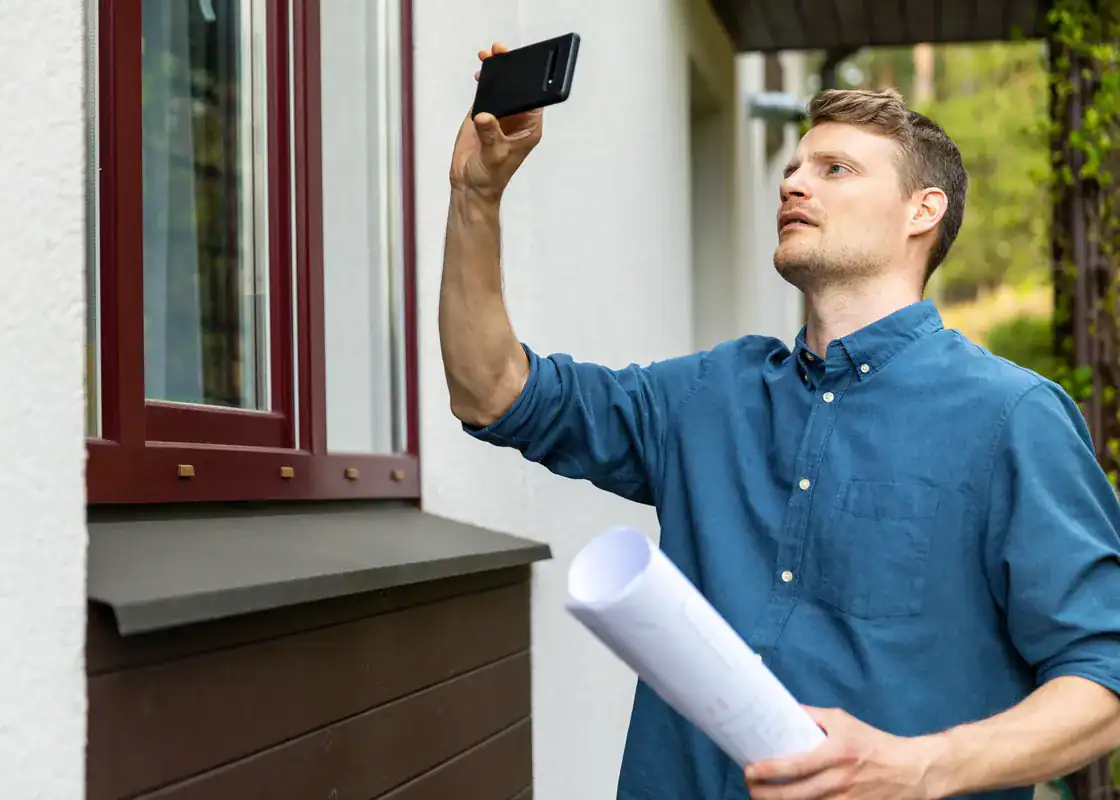
Prepare for the VA Appraisal
Once your offer is accepted, the VA assigns an independent appraiser to confirm the home's value and check it against the MPRs. Any repairs the appraiser requires have to be addressed before the loan can close. We write offers with the appraisal in mind and work with the seller's side to resolve required repairs. A VA appraisal doesn't replace a home inspection, so we'll help you schedule one too.
Close on Your Montana Home
After your lender's underwriter clears the file, you'll receive a Closing Disclosure at least three business days before closing. It lists your final loan terms and costs. We track the file through underwriting, review the Closing Disclosure with you and schedule a final walkthrough of the home. At closing you'll sign your loan documents, and you take possession on the terms set in your purchase contract.